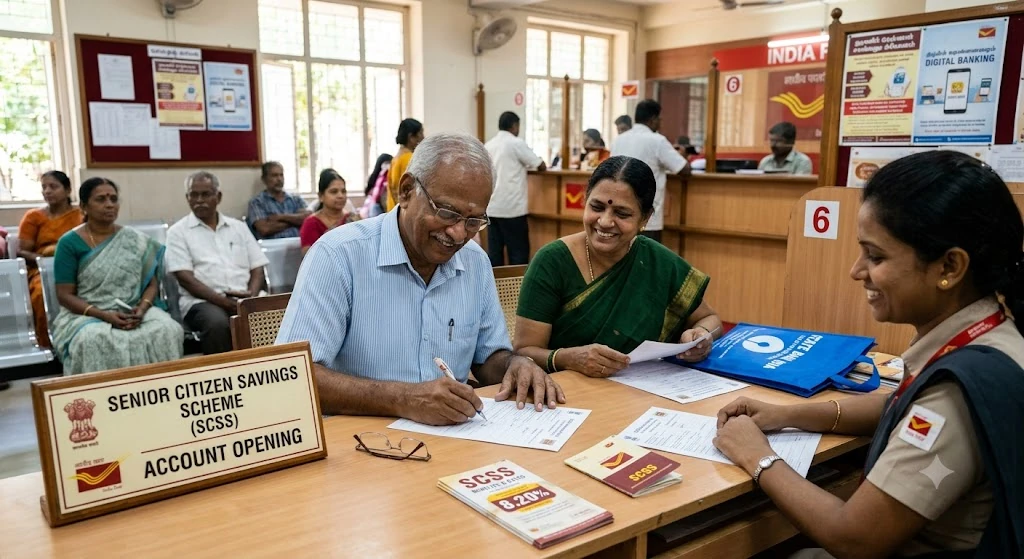
Master Your Retirement Income with SCSS
The Senior Citizen Savings Scheme (SCSS) is a government-backed investment option designed specifically to provide financial security and guaranteed regular income to retirees in India. Offering a sovereign guarantee and higher returns than most conventional fixed deposits, SCSS remains one of the most reliable wealth-preservation avenues for senior citizens.
Key Features & Highlights (2026)
- Current Interest Rate: 8.2% per annum (reviewed quarterly by the Government of India).
- Investment Limits: Minimum deposit of ₹1,000 up to a maximum cap of ₹30 Lakh per individual. Couples can invest up to ₹60 Lakh across separate individual accounts.
- Tenure: Fixed maturity period of 5 years, extendable once for an additional 3 years upon request.
- Payout Frequency: Guaranteed quarterly payout credited directly on the 1st working day of April, July, October, and January.
- Risk Level: Zero sovereign risk (backed directly by the Ministry of Finance).
Eligibility Criteria
To open an SCSS account at any designated post office or major public/private bank, an applicant must fall into one of the following categories:
- Senior Citizens: Resident individuals aged 60 years or above.
- Early Retirees (VRS / Superannuation): Individuals aged 55 to 60 years who have retired under voluntary or regular retirement schemes, provided the account is opened within 1 month of receiving retirement benefits.
- Retired Defence Personnel: Retired military personnel aged 50 years or above (excluding civilian defence employees) subject to standard timelines.
- Joint Accounts: Allowed only with a spouse. The primary applicant is considered the sole owner of the funds.
Note: Non-Resident Indians (NRIs) and Hindu Undivided Families (HUFs) are not eligible to open SCSS accounts.
Tax Implications & Section 80C Benefits
- Tax Deduction: Principal deposits up to ₹1.5 Lakh per financial year qualify for tax deductions under Section 80C of the Income Tax Act (under the Old Tax Regime).
- Taxability of Interest: Interest income earned from SCSS is fully taxable based on your applicable income tax slab.
- Tax Deducted at Source (TDS): TDS applies if the total interest payout exceeds ₹50,000 to ₹1,00,000 annually. Senior citizens with taxable income below the exemption threshold can submit Form 15H / Form 121 to avoid TDS deduction.
SCSS Returns Calculation Table
| Principal Invested | Quarterly Interest Income | Annual Interest Income | Total Interest Earned (5 Years) |
| ₹5,00,000 | ₹10,250 | ₹41,000 | ₹2,05,000 |
| ₹10,00,000 | ₹20,500 | ₹82,000 | ₹4,10,000 |
| ₹15,00,000 | ₹30,750 | ₹1,23,000 | ₹6,15,000 |
| ₹30,00,000 | ₹61,500 | ₹2,46,000 | ₹12,30,000 |
Premature Withdrawal Rules & Penalties
While funds are meant to remain locked in for 5 years, premature closure is permitted subject to specific deductions:
- Before 1 Year: No interest is payable. Any interest already paid out is recovered directly from the principal balance.
- Between 1 and 2 Years: A penalty equal to 1.5% of the principal deposit is deducted.
- Between 2 and 5 Years: A penalty equal to 1.0% of the principal deposit is deducted.
Comparison: SCSS vs. Bank FDs vs. Post Office MIS
| Feature | SCSS | Senior Citizen Bank FDs | Post Office MIS (POMIS) |
| Interest Rate | 8.2% p.a. | ~7.0% – 8.0% p.a. | 7.4% p.a. |
| Sovereign Safety | High (Govt. of India) | Moderate (DICGC insured up to ₹5L) | High (Govt. of India) |
| Payout Cycle | Quarterly | Monthly / Quarterly / Cumulative | Monthly |
| Section 80C Tax Savings | Yes (up to ₹1.5 Lakh) | Only on 5-Year Tax-Saving FDs | No |
| Max Limit (Single) | ₹30 Lakh | No Upper Cap | ₹9 Lakh |
How to Open an SCSS Account
- Visit any India Post Office branch or authorized commercial bank (e.g., SBI, HDFC Bank, ICICI Bank, PNB).
- Fill out Form A (SCSS Account Opening Form).
- Attach self-attested copies of your PAN Card, Aadhaar Card, age proof (Passport/Voter ID/Birth Certificate), and retirement/VRS proof (if applicable).
- Submit passport-size photographs and deposit the amount via cheque or demand draft (cash allowed up to ₹1 Lakh).
Final Verdict
For retirees seeking guaranteed capital preservation alongside predictable quarterly income, the Senior Citizen Savings Scheme remains the gold standard in Indian fixed-income investing. Maximizing your ₹30 lakh SCSS allowance provides a robust, risk-free foundation for any retirement portfolio.
Choose an image
Featured Article
For years, the default expectation after Class 12, especially for science students has been simple: clear JEE for engineering or clear NEET for medicine. If you didn't fit into those two boxes, it often felt like you were out of options. How to Choose the Right Path.
That narrative is completely outdated. Read More
What if the world's largest river wasn't on the ground?
When people think of the Amazon, they imagine a vast jungle filled with exotic wildlife, giant trees, and the mighty Amazon River. But scientists have discovered something even more astonishing hidden above the forest. A massive invisible rivers flowing through the sky. Read More
বৃক্ষছায়ায় জ্ঞানের আলোকবর্তিকা: প্রাচীন ভারতীয় শিক্ষা দর্শনের গূঢ়তত্ত্ব Read More
A brief overview of the village where Batukeshwar Dutt was born, its historical significance and how to visit. Read More

অনেক বছর ধরে প্রচলিত একটি ধারণা মানুষ তার মস্তিষ্কের মাত্র ১০% ব্যবহার করে। আধুনিক স্নায়ুবিজ্ঞান বলছে, এটি সম্পূর্ণ ভুল। আমরা আসলে আমাদের মস্তিষ্কের প্রায় সব অংশই ব্যবহার করি, শুধু একসঙ্গে নয়। প্রতিটি অঞ্চল নির্দিষ্ট কাজের জন্য দায়ী, কোনো অংশ ভাষা বোঝে, কোনো অংশ পরিকল্পনা করে, আবার অন্য অংশ আবেগ বা চলাফেরার নিয়ন্ত্রণে থাকে। Read More